
Message from the CFO


I am Kazuyoshi Kawakami, and I have recently assumed the position of CFO of Mitsubishi HC Capital. I built my career at one of Japan’s leading trading companies, serving mainly in finance and accounting roles both domestically and internationally, and have gained broad experience, including in M&A and turnaround support, through secondments to operating companies and involvement in joint ventures. Most recently, I planned and led specific initiatives to drive company-wide business portfolio restructuring, as well as the capital allocation policy and financial strategy underpinning it. Drawing on this experience, I am committed to pursuing attractive growth opportunities while strengthening the Group’s business foundation, thereby enhancing corporate value.
To date, the Group has achieved steady growth that is relatively resilient to economic fluctuations and changes in the market environment, supported by a broadly diversified business portfolio and a strong customer base. By operating across diverse business domains, we have built an earnings structure that does not depend on any particular market conditions or industry trend. I believe that our track record of delivering consistent earnings growth over the long term is one of our major strengths.
At the same time, the operating environment is becoming increasingly uncertain and complex, driven by factors such as global inflation, changes in interest rates, heightened geopolitical risks, and shifts in industrial structures brought about by advances in digital technology and AI. Under these circumstances, we recognize that enhancing corporate value requires more than simply expanding the scale of profits. It is essential that we continuously generate returns exceeding the cost of equity and improve capital efficiency.
To achieve this, in addition to improving the profitability of existing businesses, we need to continue reshaping our portfolio, optimize capital allocation based on risk-adjusted return, and strike an appropriate balance between growth investments, financial soundness, and shareholder returns. As CFO, I will drive disciplined capital deployment, including strengthening growth investments, toward achieving Our FY2031 Vision, and will work to deliver sustainable profit growth and maximize corporate value.
| FY2023 | FY2024 | FY2025 | |
|---|---|---|---|
| Gross profit | 380.0 | 462.6 | 500.1 |
| Recurring profit | 151.6 | 193.5 | 236.0 |
| Net income attributable to owners of the parent |
123.8 | 135.1 | 162.2 |
| Total assets | 11,149.8 | 11,762.3 | 13,089.5 |
| Interest-bearing debt | 8,439.7 | 8,840.7 | 9,880.3 |
| ROE (%) | 7.7 | 7.8 | 8.6 |
| ROA (%) | 1.1 | 1.2 | 1.3 |
| Payout ratio (%) | 42.9 | 42.5 | 40.7 |
The 2025 MTMP in review
Under the 2025 MTMP, we pursued our financial strategy based on the basic policy of balancing the three perspectives of growth potential, return on capital, and financial soundness toward realizing Our FY2031 Vision.
From the perspective of growth potential, we advanced the evolution and layering of business models through inorganic investments, such as taking CAI International private through full ownership and making a strategic investment in European Energy, while also making large-scale investments in highly profitable areas, including aircraft and aircraft engines. Through a combination of organic and inorganic investments, we steadily laid the groundwork for future growth and strengthened our earnings capacity.
From the perspective of return on capital, we have managed our business with a disciplined focus on the cost of equity. While rationalizing low-profitability assets and businesses with limited synergies with the Group, we repositioned capital toward higher-return opportunities. Over the five years following the business integration, we sold approximately ¥0.6 trillion of assets with an average ROA of 1.0% and invested approximately ¥0.8 trillion in assets with an average ROA of 1.8%. As a result, we steadily enhanced earnings quality and profitability, with both ROA and ROE improving each year during the 2025 MTMP period.
From the perspective of financial soundness, while continuing to provide stable shareholder returns, we maintained A credit ratings through appropriate risk management, including enhanced management of risks inherent in our businesses and more sophisticated ALM practices, and secured stable and competitively priced funding.
As a result of these initiatives, net income for FY2025, the final year of the 2025 MTMP, reached our target of ¥160.0 billion, and we increased dividends for the 27th consecutive fiscal year as a form of shareholder return. Our P/B ratio also exceeded 1.0 for the first time in September 2025. While exceeding a P/B ratio of 1.0 was an important milestone, it is by no means our destination. We will continue to execute our initiatives with discipline and consistency, aimed at sustainable growth and improved capital efficiency.
On the other hand, ROE and ROA fell short of our targets. We believe this was due to slower-than-expected progress in upgrading our portfolio mix toward higher-return assets, together with changes in the environment surrounding some businesses and the impact of yen depreciation. As a result, profit growth remained below expectations on a yen depreciation-adjusted basis.
In light of these challenges, under the 2028 MTMP, we believe it is necessary to pursue a more decisive transformation of our portfolio and optimize capital allocation to improve return on capital.

Policy and Financial Strategy under the 2028 MTMP

We position the 2028 MTMP, which started this fiscal year, as an extremely important plan that will determine whether we can achieve Our FY2031 Vision. To sustainably enhance corporate value even in an increasingly uncertain external environment, and building on the challenges identified under the 2025 MTMP, we will manage our business under the 2028 MTMP with ROE as our top priority KPI, while continuing to focus on net income.
We recognize that the Group’s cost of equity continues to be around 10% and believe that exceeding this level is the minimum threshold we must achieve. Accordingly, we have set an ROE target of 10% under the 2028 MTMP, while aspiring to achieve approximately 12% over the medium to long term.
To achieve these targets, we will optimize capital allocation by directing cash generated from existing businesses and proceeds from asset sales to growth investments and shareholder returns. In doing so, our basic policy under the 2025 MTMP of balancing growth potential, return on capital and financial soundness remains unchanged.
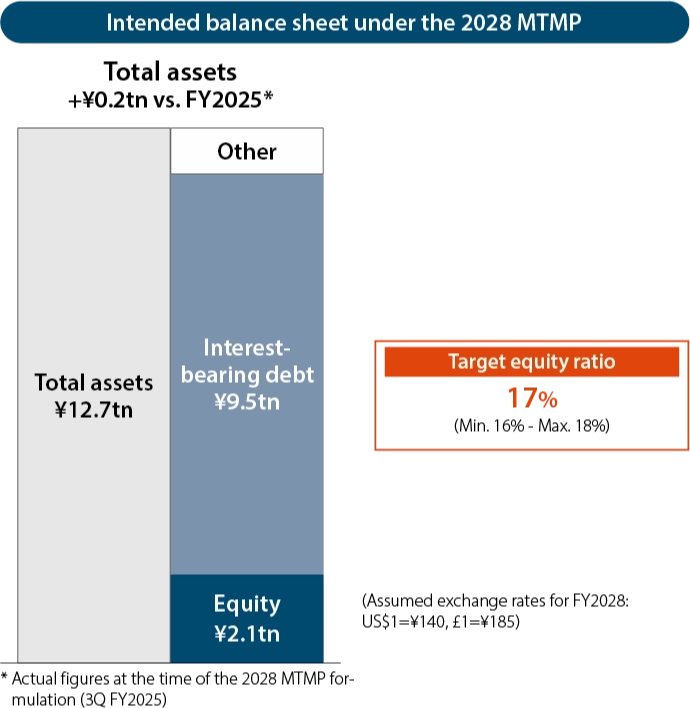
Under the 2028 MTMP, our targets are to achieve an ROE of 10% and an ROA of 1.7%, while maintaining A ratings from external credit rating agencies. We have set our target equity ratio at 17% as a level of leverage that supports the achievement of these targets while preserving financial flexibility. While increasing growth investments in line with our business strategies, we will conduct disciplined balance sheet management without holding excess capital, deepen our focus on capital-efficient management, and realize an optimal capital structure.


Optimization of Capital Allocation
First, through business portfolio repositioning with a focus on cost of capital, we will improve the earnings power of existing businesses. At the same time, we will pursue exits from low-profitability businesses and the downsizing of related assets with greater scale and speed than ever before. Specifically, we will rigorously assess business-level returns against the cost of capital (WACC) and execute approximately ¥2.1 trillion of portfolio divestments of low-profitability businesses and assets.
We will boldly allocate the funds generated through these initiatives to growth investments totaling ¥2.3 trillion: ¥1.0 trillion to inorganic investments, including M&A, and ¥1.3 trillion to investments in highly profitable existing businesses. By enhancing returns and delivering sustainable earnings growth without materially expanding total assets, we will drive the sustainable enhancement of corporate value.
Growth investments will center on the Specialized Business segments, including Aviation and Real Estate, as well as areas where the evolution and layering of business models can generate differentiated value. We will also further expand our deal pipeline and strengthen its regular review process, accelerating investment execution in high-quality investment opportunities.
Furthermore, we will continue to actively invest in human capital and our DX strategy. As the business environment changes significantly, we believe that the sources of competitive advantage lie in our people and our ability to utilize digital technology. By strengthening our recruitment capabilities and talent development, and by achieving more advanced and agile management through the use of data and AI, we will improve productivity and reinforce our competitive advantage.
In implementing these initiatives, we will also review risk management to address the emerging geopolitical risks, sharp fluctuations in macroeconomic and financial markets, and changes in the balance among risks, required capital, and its costs resulting from reshaping our business portfolio.
We will also secure a resilient platform for financial operations to prepare for risks, along with sufficient, stable, and competitive funding sources, thereby providing a strong financial foundation for strategy execution and ensuring improvement in ROA and the achievement of a 10% ROE.
Our shareholder return policy will continue to be based primarily on dividends. We will place importance on providing stable dividends by enhancing corporate value and driving sustainable profit growth while maintaining a balance between the three perspectives. In addition, in light of market expectations, we have raised the target dividend payout ratio from the previous level of 40% or higher to 45% or higher. We will continue to provide stable shareholder returns while maintaining an appropriate balance with growth investments.


Maximizing Corporate Value
As CFO, I will continually assess whether our value creation initiatives are translating into financial results and whether we have an earnings structure capable of generating returns that exceed the cost of equity, while keeping both short-term and medium- to long-term perspectives in mind. Based on these evaluations, I will promptly implement measures needed in response to changes in circumstances.
I believe the core of enhancing corporate value lies in achieving our ROE target, our top priority KPI, sustainably raising that level going forward, and translating this into an improvement in our P/B ratio. In addition, under the 2028 MTMP, we have set out our non-financial strategies and targets more clearly than ever. By advancing initiatives to achieve both financial and non-financial targets in tandem, we aim to deliver sustainable value creation over the medium to long term.
For FY2026, we forecast net income of ¥160.0 billion, a decline from ¥162.2 billion in the previous fiscal year. This is due mainly to the non-recurrence of a ¥22.8 billion one-time gain in the previous fiscal year arising from fiscal period changes at subsidiaries. Excluding this one-time factor, we expect an underlying increase in net income of more than ¥20.0 billion year on year. On the same underlying basis, our net income target for the 2028 MTMP period represents a highly ambitious growth target of more than ¥70.0 billion.
To achieve these targets, the Group’s diversified business portfolio remains the cornerstone of our ability to generate stable earnings from both income gain and asset-related gain. Under the 2028 MTMP, we will accelerate the shift toward businesses with higher profitability and further evolve the business portfolio, our robust earnings base, thereby achieving sustainable growth and maximizing corporate value.
Going forward, we will continue to engage proactively with investors, shareholders, and other stakeholders, and communicate our growth story more clearly and thoroughly. As CFO, I remain firmly committed to strengthening trust with the capital markets and delivering long-term value creation through disciplined execution of our strategy.

| 1 year | 5 years | 10 years | |||
|---|---|---|---|---|---|
| Cumulative | Annualized | Cumulative | Annualized | ||
| Mitsubishi HC Capital | +43.6% | +137.3% | +18.9% | +242.1% | +13.1% |
| TOPIX | +34.6% | +102.2% | +15.1% | +228.2% | +12.6% |
- *2Total shareholder return (TSR): Total investment return, combining returns from stock price appreciation and dividends
- *3TSR is calculated for Mitsubishi HC Capital based on cumulative dividends and stock price movements, and for TOPIX based on a total return stock price index (prepared by the Company using Bloomberg data, etc.).
- *4The values in the graph represent TSR-based market value, indexed to 100 at the closing price on March 31, 2016 (holding period through March 31, 2026).
- *5Figures for the period from End of FY2016 to End of FY2021 are based on the results of Mitsubishi UFJ Lease & Finance.